Rehnuma had never heard the word “demurrage” spoken with quite that much alarm in her voice before, and it came from her finance manager, standing in her doorway with a printed invoice in his hand.
“Do you know what this is?” he asked, placing it on her desk. She looked at the number at the bottom and felt her stomach drop slightly, the way it does when a figure appears that has no obvious home in any costing sheet you’ve ever built.
$4,200. For a single container. Sitting at the destination port for nine days past its free time, because the buyer’s documentation approval had taken longer than expected, and nobody on the factory side had been tracking the clock closely enough to flag it before the charges started accumulating.
“This isn’t in our costing,” Rehnuma said, mostly to herself, still staring at the number.
“No,” her finance manager agreed. “It never is. That’s the problem.”
The Three Words Nobody Puts in a Costing Sheet
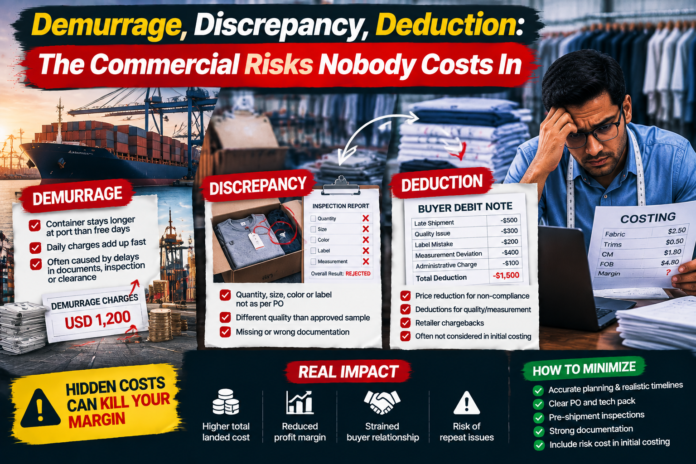
That afternoon, Rehnuma sat with her finance manager and went through, slowly and honestly, three specific risks that had quietly cost her factory real money over the past year, none of which had ever appeared, even as a line item, in any costing sheet she’d built. Demurrage. Discrepancy. Deduction. Three separate words, three separate ways an order that looked profitable on paper had ended up costing more than promised, weeks or months after the garments had already shipped.
None of these were fabric problems, or CMT problems, or even production timeline problems, the kind of risk every merchandiser is trained to watch for from day one. These lived somewhere else entirely — in the commercial and financial mechanics of actually getting paid for an order, a part of the process most merchandisers, Rehnuma included, had never been taught to think about as their own responsibility at all.
Demurrage: The Clock That Starts the Moment Nobody’s Watching
Demurrage, her finance manager explained, is the charge a shipping line applies when a container sits at port longer than its allotted “free time” — typically a handful of days, sometimes longer depending on the shipping line and destination — before being cleared and moved out. Every day past that free window, the charge accumulates, sometimes significantly, and it lands directly on whoever is contractually responsible for that leg of the shipment, which, depending on the shipping terms agreed with the buyer, could well be the factory.
The container that generated that $4,200 charge hadn’t sat idle because of anything the factory did wrong. The delay came from the buyer’s side — their customs documentation, their import clearance process, moving slower than usual that particular week. But the shipping terms on that specific order meant the factory carried responsibility for demurrage regardless of whose delay actually caused it, and nobody had been tracking the container’s port clock closely enough to catch the problem while there was still time to push the buyer for faster clearance, or to explore other options before the charges piled up.
“This is the part that surprises merchandisers most,” her finance manager said. “You think your job ends when the container leaves your factory gate. Financially, depending on your shipping terms, it often doesn’t. Something happening on a dock on the other side of the world, weeks after your garments left, can still come back and eat your margin.”
Discrepancy: When the Paperwork Doesn’t Quite Match
The second risk was one Rehnuma had actually heard of before, vaguely, without ever fully understanding how much it could actually cost. Discrepancy fees, in the context of letters of credit, are charges that arise when the shipping documents presented to the bank don’t exactly match what the letter of credit specifies — a date slightly off, a quantity figure that doesn’t precisely reconcile, a description of goods phrased differently than the LC’s exact wording.
Banks, her finance manager explained, are strict about this, almost mechanically so, because their role in an LC transaction is specifically to verify documents match, not to use judgment about whether a mismatch is meaningful or trivial. A discrepancy, even a small, obviously unintentional one, can trigger a fee, delay payment, or in more serious cases, give the buyer’s bank grounds to refuse payment entirely until the discrepancy is formally resolved, sometimes requiring buyer approval to waive it.
Rehnuma pulled up records from an order earlier that year where payment had been delayed almost three weeks, something she remembered being frustrated about at the time without ever fully tracing the cause. It turned out a shipping document had listed a slightly different port name abbreviation than what the LC specified, a genuinely minor difference that meant nothing to anyone reading it casually, but was enough to trigger a formal discrepancy under the bank’s strict document-matching process. The delay in payment, and the fee charged to resolve it, had simply been absorbed quietly into that order’s final numbers, never flagged as its own distinct, preventable cost.
“The frustrating part,” her finance manager said, “is that discrepancies are almost always avoidable. It’s not a real commercial risk in the sense of something unpredictable. It’s an accuracy problem, a documentation problem, and it costs money anyway, exactly like a real risk would, if nobody’s specifically responsible for catching it before documents go to the bank.”
Deduction: The Charge That Shows Up After the Money’s Already Gone
The third risk was the one that had actually prompted the conversation that afternoon, the one that had cost the most, cumulatively, across the past year without Rehnuma ever quite connecting the dots.
Buyer deductions — charge-backs applied by the buyer after goods have already shipped and, in some cases, after payment has technically already been processed, for issues ranging from late shipment penalties, to quality claims on a portion of the order, to compliance audit shortfalls, to charges for the buyer having to expedite freight because the factory’s own shipment ran late. These arrive, often, as a simple deduction from the next payment, or as a separate debit note, sometimes weeks or months after the order itself felt, from the factory’s perspective, completely finished and closed.
Going through the past year’s records together, Rehnuma and her finance manager found deductions on four separate orders, none individually dramatic, but adding up, across the year, to a real, meaningful percentage of what should have been that year’s overall margin. A late shipment penalty on one order, clearly specified in the buyer’s terms but never actually built into the original costing as a real risk, since the order had been expected to ship on time. A quality claim on a small percentage of another order, deducted directly from payment rather than resolved through negotiation, because the factory hadn’t disputed it within the buyer’s stated claim window. A compliance-related charge-back on a third, tied to a documentation gap during a social audit that the factory had genuinely fixed afterward, but too late to avoid the deduction already applied for that specific shipment.
“Each one of these, on its own, we treated as a one-off,” her finance manager said. “A bad week, a difficult buyer, bad luck. But look at four of them together, across a year. That’s not bad luck. That’s a pattern nobody was tracking as a pattern, because each deduction got buried in a different order’s individual closeout, instead of being pulled together and looked at as its own category of risk.”
Why These Three Risks Hide So Well
Sitting with all three examples laid out together, Rehnuma started to understand exactly why these particular risks had stayed invisible for so long, in a way that fabric waste or trim wastage, despite being just as real, almost never did.
Fabric and trim costs get measured against a costing sheet immediately, at the point of purchase and consumption, while the order is still active and everyone’s attention is still on it. Demurrage, discrepancy, and deduction all happen later, sometimes much later, after the garments have shipped, after the order feels, emotionally and organizationally, already finished. By the time a demurrage invoice or a deduction notice actually arrives, the merchandiser’s attention has usually already moved fully onto the next order, and the charge gets absorbed, quietly, into finance’s general accounting, rarely traced back to a specific decision or a specific gap in the original costing that could have anticipated it.
They also, unlike fabric or CMT, don’t feel like the merchandiser’s responsibility at all, on first instinct. Demurrage feels like a shipping company’s problem, or the buyer’s problem, since their customs delay caused it. Discrepancy feels like a banking or documentation department’s problem. Deduction feels like something that happens to an order after the merchandiser’s real job, getting it made and shipped, is already done. None of these instincts are entirely wrong. But all three risks are still commercial realities that shape whether an order was actually profitable, and pretending they belong entirely to someone else’s department doesn’t make their cost disappear from the factory’s actual bottom line.
What Rehnuma Started Doing Differently
The changes she made afterward weren’t complicated, and none of them required a new department or a large new process. They required treating these three risks as real costing inputs, the same way she already treated fabric wastage or CMT ramp-up time, instead of leaving them as invisible, after-the-fact surprises.
For demurrage, she started checking shipping terms on every order at the quoting stage, specifically noting whether the factory carried port-side demurrage risk under the agreed terms, and building a small contingency allowance into orders where that risk genuinely existed, particularly with buyers whose customs clearance had historically run slow. She also started actively tracking container status after shipment, rather than considering her job finished the moment the container left the factory gate, flagging any unusual delay early enough to push for faster clearance before free time actually expired.
For discrepancy, she worked with her documentation team to build a simple final check — comparing every shipping document against the exact wording of the letter of credit, line by line, before submission to the bank, rather than trusting that “close enough” would hold up against a bank’s mechanically strict matching process. It added maybe twenty minutes to document preparation. It had already, in the months since, caught two potential discrepancies before they became actual delayed payments.
For deductions, she started keeping a running, factory-wide log, not order by order in isolation, but as its own tracked category, so patterns like the one she’d just discovered with her finance manager would surface much earlier, before a full year’s worth of individually small deductions quietly added up into something significant enough to demand attention. She also started reading buyer terms and conditions for penalty and claim clauses more carefully at the negotiation stage, rather than treating that section as standard boilerplate nobody actually needed to study closely.
Why This Belongs on the Merchandiser’s Desk, Not Just Finance’s
Talking it through afterward, Rehnuma understood why her finance manager had walked into her office with that invoice instead of simply processing it quietly through the accounts, the way it might have happened in past years. A merchandiser is the person who actually understands the order end to end — the buyer’s history, the shipping terms agreed during negotiation, the realistic risk of delay on a specific route or with a specific buyer’s customs process. Finance can track the charges after they happen. Only someone sitting where Rehnuma sits can actually anticipate them, price for them honestly, and in some cases, prevent them from happening at all.
“You already think about risk,” her finance manager told her, near the end of that conversation. “Fabric price risk, wastage risk, CMT risk. This is the same instinct, just pointed somewhere it usually never goes. The order isn’t actually finished when the container leaves your gate. Financially, it’s not finished until the payment clears clean, with nothing deducted, nothing delayed, nothing charged back weeks later that nobody saw coming.”
The Real Lesson in a $4,200 Invoice
What stayed with Rehnuma longest wasn’t really the specific number on that demurrage invoice, even though it was large enough to sting. It was realizing how much of an order’s true profitability gets decided in places a merchandiser doesn’t naturally think to look — not in the cutting room, not on the sewing line, not even in the finishing department, but in a shipping term negotiated months earlier, in a document comparison nobody double-checked, in a deduction clause read once and then forgotten.
A costing sheet that stops at “FOB price times quantity” is only telling part of the story. The real, final margin on any order depends just as much on what happens after the goods leave the factory as on what happens while they’re being made — and that’s exactly the part most merchandisers, trained carefully to watch fabric, CMT, and production timelines, have simply never been taught to watch at all, until an invoice like Rehnuma’s lands on their desk, unexplained, months after the order already felt done.