Tuhin noticed it first in a place nobody really pays attention to — the empty rows in his line-loading chart.
He’d been building line allocation plans for almost nine years, and there was a rhythm to it he’d never had to think about consciously, the way you don’t think about breathing. Big buyer confirms a bulk order. Order gets slotted onto two, sometimes three lines for six to eight weeks straight. Next big order lines up right behind it, seamless, one bulk run flowing into the next. That rhythm had been the entire shape of his job for years.
This season, the chart looked different, and it took him a while to understand why it was bothering him so much. Instead of two or three big, clean blocks of production, he had six smaller ones, scattered, with awkward gaps between them that his old planning instincts didn’t know how to fill. Smaller quantities. Shorter runs. More styles, more colorways, more frequent changeovers. Nothing was actually wrong, exactly. It just didn’t fit the shape his whole career had trained him to expect.
He mentioned it to his factory’s commercial director, a calm, direct woman named Farida apa, half expecting her to tell him it was just a slow quarter, nothing structural, the kind of dip that corrects itself in a season or two.
“It’s not a dip,” she told him. “I think this is just what order books look like now.”
The Chart That Explains the Chart
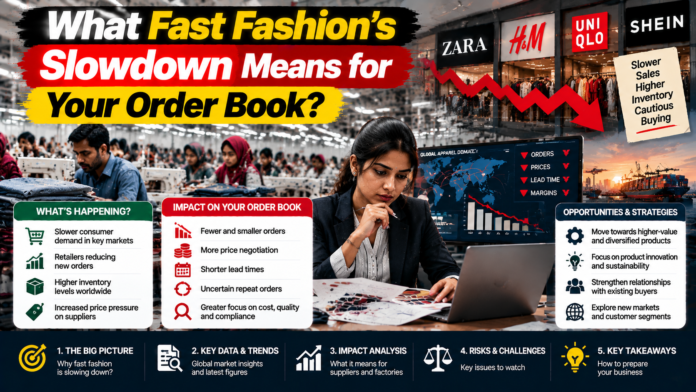
Farida apa had been reading industry reports more closely than Tuhin had, and she pulled a few numbers up that put language to what his line-loading chart had already been quietly telling him. US textile and apparel import volume had fallen 8.5 percent in the first seven months of the year compared to the year before. Europe’s story looked similar, with clothing import volumes into the EU dropping over 5 percent in the first quarter, and the prices buyers were willing to pay falling even faster than the volumes themselves.
“Look at this part carefully,” she said, pointing to a line in one report. Analysts were describing what was happening not as a temporary slowdown that would snap back once consumer confidence recovered, but as a structural reset — weaker demand, thinner pricing power, and brands responding by placing smaller, more carefully planned orders instead of the large, confident bulk commitments they used to make a season at a time.
That phrase, “smaller, more carefully planned orders,” landed differently for Tuhin once he heard it out loud. It wasn’t an abstract industry trend anymore. It was literally the shape of his own line-loading chart, described back to him in a market report he’d never bothered to read.
Why Buyers Are Actually Doing This
Tuhin’s first instinct, understandably, was to feel a little defensive on behalf of his factory. Smaller orders felt, emotionally, like buyers trusting them less, like something the factory had done wrong. Farida apa pushed back on that read gently but firmly.
“This isn’t about us,” she said. “Their own customers have changed how they shop. Brands are protecting themselves from getting stuck with inventory nobody wants, the way a lot of them did during past overproduction. It’s cheaper for them to place a smaller order, sell through it, and reorder if it works, than to commit big and get it wrong.”
That reasoning made sense once Tuhin actually sat with it. Fast fashion, at its core, had always been built on speed and volume — huge quantities, produced fast, sold cheap, replaced constantly. But that same model, the one that had defined so much of Bangladesh’s growth for two decades, was exactly the model buyers were now quietly backing away from, not because they’d stopped wanting speed, but because the pure, high-volume version of it had stopped reliably making them money. Weaker consumer spending meant garments sitting unsold longer, and unsold garments sitting in a warehouse is one of the most expensive things that can happen to a fashion brand’s balance sheet.
Smaller, more frequent orders were the buyer’s way of managing that risk. Less committed inventory upfront. Faster ability to react to what was actually selling. Reorder the winners, quietly drop the ones that didn’t move. From the buyer’s side, it was simply smart risk management in a market that had gotten less predictable. From Tuhin’s side, sitting with a line-loading chart full of awkward gaps, it looked like chaos.
The Factory That Didn’t Adjust
Farida apa told him about a sister factory in their group, a larger unit specializing almost entirely in basic knit tops for one major fast-fashion buyer, that hadn’t adjusted its own planning assumptions when this same shift started showing up in their order pattern about a year earlier.
That factory had kept its line structure built entirely around long, uninterrupted bulk runs, the same setup that had worked beautifully for years. When their buyer’s orders started arriving smaller and more frequent instead of one confident seasonal commitment, the factory’s rigid line setup struggled to adapt. Every changeover between smaller orders cost them real efficiency, because their lines, their supervisors, their whole planning rhythm had been optimized for long, uninterrupted runs, not for the kind of frequent switching this new order pattern actually demanded. Utilization rates on those lines had genuinely dropped, not because there wasn’t enough total work coming in, but because the work was arriving in a shape their factory wasn’t structured to absorb efficiently.
“They’re not losing the buyer,” Farida apa said. “They’re losing efficiency on every single order, because they kept planning for a version of demand that isn’t really coming back the way it used to. That’s the real risk in this shift. It’s not that the work disappears. It’s that the factories still planned around the old rhythm end up quietly bleeding margin on every order, one small inefficiency at a time.”
Rebuilding the Line Chart Around a Different Rhythm
That conversation pushed Tuhin to actually rebuild how he thought about line allocation, rather than just hoping the gaps in his chart would fill themselves back in once things “normalized.”
The first change was accepting that changeovers, not just production days, needed real planning attention now. In the old bulk-heavy rhythm, changeover time between orders was a small, almost forgettable line item, because it happened rarely. In this new rhythm, with smaller orders arriving more frequently, changeover time became a real, recurring cost that needed to be planned for explicitly, the same way Sabbir had learned to plan for smaller hidden checkpoints between the big visible stages of a single order.
The second change was rethinking which lines handled which kind of work. Instead of treating every line as interchangeable, capable of running any order thrown at it, Tuhin started designating a couple of lines specifically for faster-turnaround, smaller-batch work, with supervisors and operators who got genuinely good, through repetition, at handling frequent style and color changes efficiently. The remaining lines stayed configured for whatever larger, longer runs still came through, which, Farida apa was careful to point out, hadn’t disappeared entirely — they’d just become a smaller share of the total order book than they used to be.
The third change was less about planning mechanics and more about mindset, and it was the hardest one to actually internalize. Tuhin had to stop measuring a “good” week by how full and uninterrupted his line-loading chart looked, the old standard that had served him well for years, and start measuring it by how efficiently the factory moved through whatever mix of order sizes actually showed up that week. A chart full of smaller, well-managed blocks, each one profitable on its own terms, was a genuinely good outcome now, even if it looked messier on paper than the clean, uninterrupted blocks of a bulk-heavy season used to.
The Opportunity Hiding Inside the Disruption
What surprised Tuhin most, once he’d actually adjusted, wasn’t just that the factory survived the shift. It was that a few buyers, over the following months, started specifically seeking out factories that could handle exactly this kind of smaller, faster order pattern well, rather than treating it as an inconvenience to be tolerated.
A newer buyer relationship, one their sales team had been quietly cultivating, turned out to represent exactly the kind of brand this whole shift was creating — a smaller, more focused label that deliberately avoided the traditional bulk wholesale model precisely because it didn’t want to compete purely on volume and price against giant fast-fashion players. This buyer wanted smaller runs, faster turnaround, and, critically, a factory that wouldn’t treat their orders as second priority behind some other buyer’s bigger bulk commitment.
Tuhin’s newly restructured lines, the ones built specifically to handle frequent changeovers efficiently, turned out to be exactly what this buyer needed. What had started as a defensive adjustment, a reaction to a shrinking and fragmenting order book, had accidentally positioned part of the factory to compete for a genuinely different kind of buyer relationship, one less exposed to the same pricing pressure squeezing the pure high-volume fast-fashion segment.
Farida apa had seen this pattern before other people in the industry started naming it clearly. The buyers still placing large, confident bulk orders were increasingly the ones who’d invested in genuine efficiency, automation, and diversified product capability, the kind of factories that could hold prices steady even as overall demand weakened. Everyone else was either getting squeezed on price, chasing volume that was becoming scarcer and less reliable every season, or adapting toward this newer, smaller-batch, faster-turnaround model that a different, growing segment of buyers actually wanted.
What This Actually Means for an Order Book
Sitting with his rebuilt line-loading chart months later, Tuhin thought back to how alarmed he’d felt the first time he saw those awkward gaps between smaller order blocks, how much it had looked, at first glance, like something was going wrong.
Nothing had gone wrong, exactly. The shape of demand itself had genuinely changed, driven by consumer spending patterns and buyer risk management decisions happening thousands of miles away, in board rooms Tuhin would never sit in. What had actually gone wrong, briefly, was that his planning instincts, built over nine years around one specific rhythm of demand, hadn’t yet caught up to a different rhythm that had quietly become the new normal.
The factories struggling hardest right now, from what Tuhin could see across his own industry contacts, weren’t necessarily the ones getting smaller orders. They were the ones still planning, pricing, and staffing as if the old bulk rhythm would eventually come back exactly as it used to be, rather than adapting their actual operations to the order book that was genuinely showing up in front of them, season after season.
Tuhin still hopes for the occasional big bulk order, the kind that fills a line cleanly for six straight weeks with satisfying, uninterrupted efficiency. Those orders haven’t vanished entirely, and probably never will completely. But he’s stopped treating them as the only version of a healthy order book. A line-loading chart full of smaller, well-managed, efficiently run blocks isn’t a sign that something’s wrong anymore. For a lot of merchandisers and planners across this industry right now, quietly, it’s simply what a healthy order book looks like these days — and the ones who figure that out earliest are the ones least likely to be caught flat-footed by a market that has already, mostly, moved on without waiting for anyone’s permission.